The Bond Market Knows Something Your Stock Portfolio Doesn't
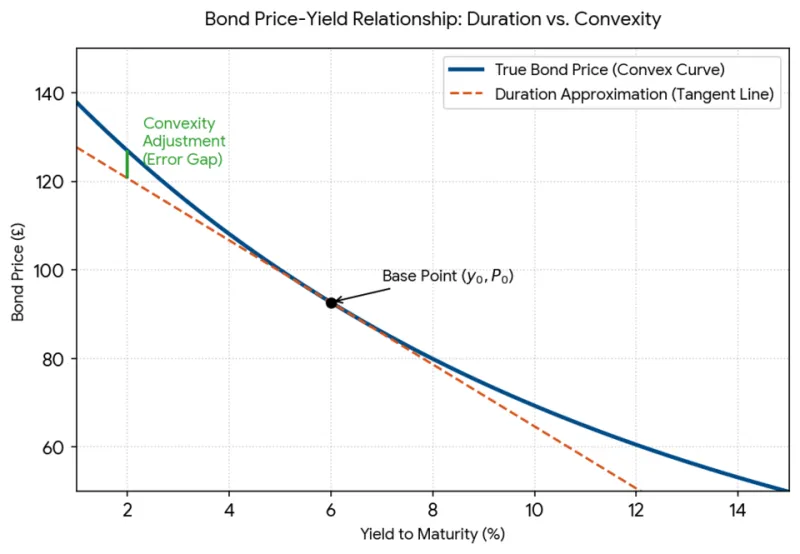
Photo: SpookiePuppy, CC0, via Wikimedia Commons
The US bond market is the largest and most liquid financial market on the planet, dwarfing equities in both size and the sophistication of its participants. Yet most retail investors treat it as background noise—something relevant only to retirees seeking income or to the Federal Reserve in its monetary policy deliberations.
This is a costly oversight. Fixed income markets routinely price in macroeconomic shifts weeks or months before equities react. The investors who learn to interpret these signals—without needing to become bond traders themselves—gain access to a forward-looking compass that can meaningfully improve portfolio positioning.
Why Bonds Lead and Stocks Follow
To understand why bond markets tend to anticipate equity moves, it helps to think about who participates in each market.
The US Treasury market and the investment-grade corporate bond market are dominated by large institutional participants: central banks, sovereign wealth funds, pension funds, and insurance companies. These entities employ teams of economists and analysts focused exclusively on macroeconomic forecasting. Their trades, which move in enormous size, reflect highly researched views on inflation, growth, and monetary policy.
The equity market, by contrast, is considerably more democratized and more susceptible to sentiment, narrative, and momentum. When institutional bond investors begin repositioning based on their macro outlook, the signal is embedded in yield movements long before it shows up in stock prices.
For retail investors, learning to read those yield movements is the equivalent of gaining access to a leading indicator that costs nothing to monitor.
The Yield Curve: Your First Instrument
The yield curve—a simple graph plotting Treasury yields across different maturities, from three-month bills to thirty-year bonds—is the most widely followed fixed income signal, and for good reason.
Under normal economic conditions, longer-dated bonds yield more than shorter-dated ones. Investors demand a premium for locking up capital over longer periods, given greater uncertainty about inflation and interest rates. This produces an upward-sloping, or normal, yield curve.
When the curve flattens—when the spread between short-term and long-term yields narrows—it typically signals that bond investors expect slower growth ahead. When it inverts—when short-term yields actually exceed long-term ones—it has historically been one of the most reliable recession indicators available. Every US recession since the 1970s has been preceded by a yield curve inversion, though the lag between inversion and recession can range from six months to nearly two years.
For equity investors, the practical implication is straightforward. A flattening or inverted curve warrants a more defensive posture: reducing exposure to cyclical sectors such as industrials and consumer discretionary, and considering a shift toward defensives like utilities, consumer staples, and healthcare. It does not mean liquidating equities, but it does mean adjusting risk accordingly.
Conversely, when an inverted curve begins to re-steepen—when long-term yields start rising relative to short-term yields—this often signals that the market is beginning to price in recovery. Historically, the steepening phase that follows an inversion has been associated with improving economic conditions and the early stages of equity bull markets.
Credit Spreads: The Risk Appetite Barometer
Beyond the Treasury curve, corporate bond spreads offer a second, highly actionable signal.
Credit spreads represent the yield premium that corporate bond issuers must pay above comparable Treasury yields. When investors are confident in the economy and comfortable with risk, they accept narrower spreads—they do not require much additional compensation to hold corporate debt over government bonds. When anxiety rises, spreads widen as investors demand greater compensation for default risk.
This dynamic makes credit spreads an effective real-time gauge of institutional risk appetite. Widening high-yield spreads, in particular, often precede equity market stress by days or weeks. High-yield issuers—companies with below-investment-grade credit ratings—are the most economically sensitive borrowers. When institutional investors begin to worry about their ability to service debt, the sell-off in high-yield bonds frequently foreshadows a broader risk-off move in equities.
Retail investors can monitor credit spread data through resources such as the Federal Reserve Bank of St. Louis's FRED database, which publishes the ICE BofA US High Yield Index Option-Adjusted Spread on a daily basis, free of charge. A sustained move higher in this spread—particularly if it accelerates—is a meaningful warning signal worth incorporating into portfolio decision-making.
What Rising Yields Actually Mean for Your Stocks
One of the most common sources of confusion for retail investors is the relationship between rising Treasury yields and equity valuations. The two are more directly connected than many realize.
Equity valuation models—particularly for growth stocks—rely on discounting future earnings back to present value. The discount rate used in these models is typically anchored to the risk-free rate, which is derived from Treasury yields. When yields rise, the discount rate rises, and the present value of future earnings falls. This is why growth stocks and technology companies, whose valuations are weighted heavily toward earnings expected years in the future, tend to be especially sensitive to rising yields.
During 2022, this mechanism played out with unusual clarity. As the Federal Reserve raised rates aggressively and Treasury yields surged, growth and technology stocks—which had been priced for a prolonged low-rate environment—experienced steep multiple compression even in cases where underlying business fundamentals remained intact. Investors who were monitoring yield movements had a meaningful early warning that this repricing was coming.
Practically speaking, when the ten-year Treasury yield is rising rapidly, it is worth reassessing the duration of your equity portfolio—that is, how far into the future the earnings underpinning your valuations are projected. Shorter-duration equities, such as value stocks and dividend payers with near-term earnings, tend to be more resilient in rising-rate environments.
Building Fixed Income Awareness Into Your Routine
None of this requires becoming a fixed income specialist. The goal is simply to incorporate a handful of observable metrics into your regular market monitoring.
A practical weekly routine might include checking the current shape of the Treasury yield curve—specifically the spread between the two-year and ten-year yields, which is widely published and easy to track. Review the high-yield credit spread to assess whether institutional risk appetite is expanding or contracting. And note the direction and pace of change in the ten-year yield relative to recent months, as the rate of change often matters as much as the absolute level.
These three data points, reviewed consistently, will not predict every market move. But they will help you maintain a more calibrated sense of where the macro environment is heading—and avoid the experience of being surprised by equity market moves that the bond market had been signaling for weeks.
Listening to the Market's Most Informed Participants
The bond market is not infallible, and no single indicator should drive portfolio decisions in isolation. But it represents the collective judgment of some of the most analytically rigorous institutional investors in the world, and it speaks a language that is accessible to any retail investor willing to learn a few basic terms.
At Shri Stock Tips, we believe that smarter investing means using every available tool—not just the most visible ones. The equity market gets the headlines. The bond market often gets the story right first.